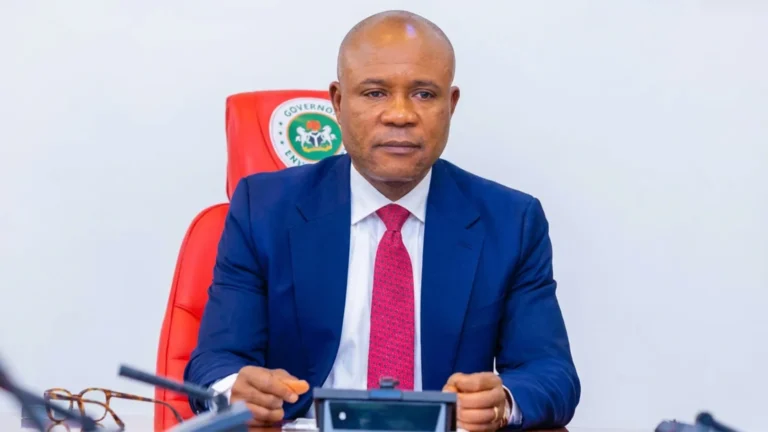
Governor of the Central Bank of Nigeria, Olayemi Cardoso, has announced that the apex bank is targeting 95 percent financial inclusion and fraud losses of less than 0.001 percent of total digital transactions by 2028.
The ambitious targets form part of the CBN’s broader strategy to deepen access to financial services, strengthen confidence in Nigeria’s digital payment ecosystem and accelerate the country’s transition toward a more inclusive and technology-driven economy.
According to Cardoso, expanding financial inclusion remains essential for economic growth, poverty reduction and sustainable development. Therefore, the CBN continues to implement policies designed to ensure that more Nigerians can access and benefit from formal financial services.
Driving Financial Inclusion Across Nigeria
Financial inclusion has become a key priority for policymakers because it enables individuals and businesses to participate more effectively in the economy.
Access to banking services, savings products, credit facilities and digital payment platforms can improve financial security and create opportunities for economic advancement.
Cardoso noted that achieving 95 percent financial inclusion would represent a major milestone in Nigeria’s financial sector development.
Furthermore, greater inclusion can help bridge economic disparities by extending financial services to underserved and previously excluded populations.
The CBN believes that technology and innovation will play a crucial role in reaching this objective.
Strengthening the Digital Economy
Nigeria has witnessed significant growth in digital payments and electronic financial services in recent years.
As more individuals and businesses adopt digital platforms, the demand for secure and efficient financial systems continues to increase.
Consequently, the CBN is focused on creating an environment that supports innovation while maintaining trust and reliability within the financial ecosystem.
Cardoso emphasized that a strong digital payment infrastructure can boost productivity, encourage entrepreneurship and facilitate economic activity across multiple sectors.
Moreover, digital finance can help reduce transaction costs and improve convenience for millions of users.
Reducing Fraud to Build Public Confidence
Alongside financial inclusion goals, the CBN is also targeting fraud losses of less than 0.001 percent of total digital transactions by 2028.
Maintaining security within the digital financial system remains critical to sustaining public trust and encouraging broader adoption of electronic payment channels.
Cardoso explained that reducing fraud requires continuous investment in technology, risk management systems and regulatory oversight.
Additionally, collaboration among financial institutions, technology providers and regulatory agencies will be essential for strengthening cybersecurity and preventing financial crimes.
A secure financial ecosystem, he noted, creates confidence for consumers, businesses and investors alike.
Leveraging Innovation and Technology
The CBN’s strategy places significant emphasis on technology-driven solutions.
Digital banking platforms, mobile financial services, fintech innovations and agent banking networks continue to expand access to financial services across the country.
These innovations have helped reach populations in rural and underserved areas where traditional banking infrastructure may be limited.
Consequently, technology remains a powerful tool for advancing financial inclusion and supporting economic participation.
Furthermore, innovation can help improve service delivery while enhancing efficiency within the financial sector.
Supporting Economic Development
Financial inclusion contributes directly to economic growth by enabling individuals and businesses to access resources needed for investment and productivity.
When more people participate in the formal financial system, opportunities for savings, credit access and wealth creation increase.
The CBN believes that expanding financial access will support entrepreneurship, stimulate economic activity and strengthen overall financial stability.
Moreover, a secure and inclusive financial system can contribute to broader development objectives, including job creation and poverty reduction.
Looking Ahead
The commitment by Olayemi Cardoso and the Central Bank of Nigeria to achieve 95 percent financial inclusion and minimal fraud losses by 2028 reflects a bold vision for Nigeria’s financial future.
As digital finance continues to evolve, stakeholders across the banking, technology and regulatory sectors will play important roles in achieving these objectives.
For many observers, the targets highlight the growing importance of innovation, security and accessibility in building a modern financial system.
Ultimately, stronger financial inclusion and enhanced digital security can help unlock economic opportunities, strengthen public confidence and support Nigeria’s long-term development aspirations.
About The Author